

A quiet ledger that speaks at dusk
The card arrives like a small moonlight—polished, promising rewards that glint: cashback on rides, merchant discounts, and an easy interface. The truth is comparative: some wins are broad, some are narrow. The didi card joins a crowded sky of credit products, offering cashback mechanics and a simple onboarding that feels like breath after a long ride. For drivers and frequent riders in Mexico City, for example, the convenience maps directly to daily savings and fewer cancelled trips, a practical anchor for real-world value.
Ledger lines: fees, APR, and subtle margins
Costs live in small print and in timing: annual fee, billing cycle quirks, interest rate on revolving balances. DiDi’s card discloses an APR that compares favorably to some bank offers, but the real cost shows when balances carry month to month. Cashback is generous on specific categories, yet merchant-level fees and reward caps can erode headline returns. Think of cashback as a river: useful when you channel it straight to on-time payments; wasteful when it tries to fill a bucket with holes.
Where the comparisons sharpen
Lay DiDi’s card beside a mainstream bank credit card and a pure fintech cashback product. The bank card may offer broader travel perks and higher credit limits; fintech peers might push instant payouts and fewer branch requirements. DiDi lands in the middle: targeted merchant benefits, integrated ride rewards, and easier credit access for drivers. Industry terms: credit limit and annual fee often decide which side you pick—stability or specialized savings.
How application and approvals really play out
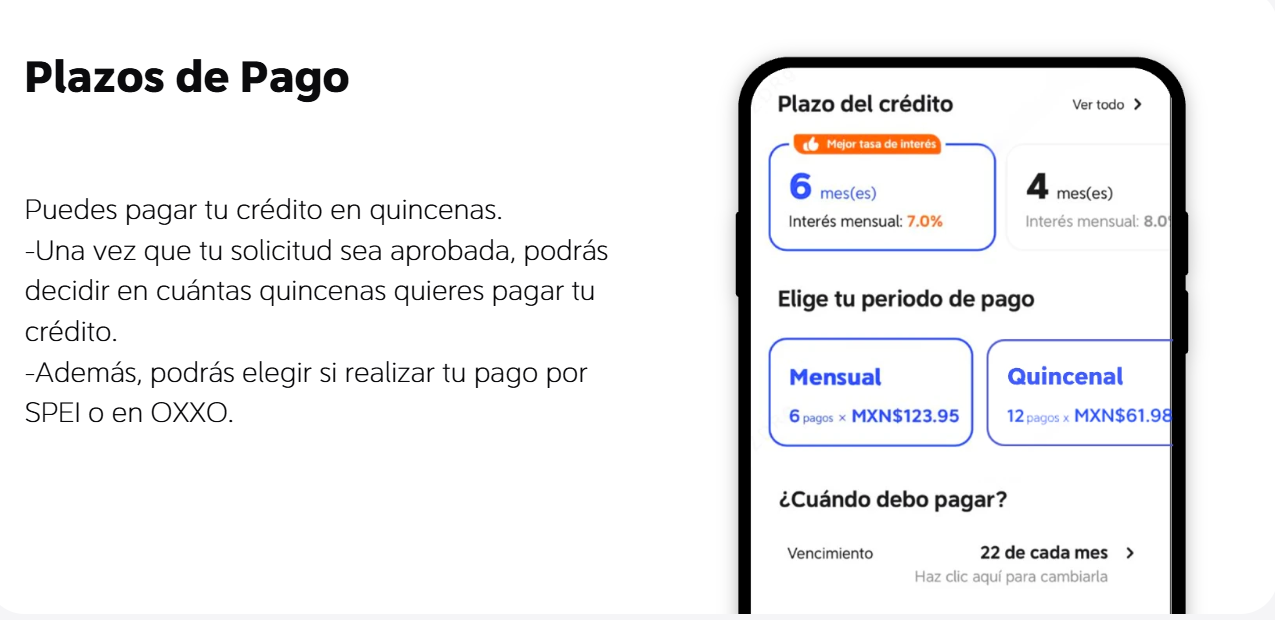
Applying requires the usual documents, a short credit check, and consistent identity verification—faster than legacy banks, slower than some app-only challengers. If you want to proceed, the practical link is here: didi card solicitar, where the digital steps are spelled out. Be mindful of the common mistakes: carrying a balance to chase rewards, or ignoring billing cycles that trigger interest immediately. A small misstep in timing can nullify months of cashback.
Everyday tactics that preserve value
Use the card for high-cashback categories and clear the statement each month. Track the billing cycle like a tide—pay before the interest rolls in. Also, move rewards into practical uses (ride discounts, daily purchases) rather than letting them sit and devalue. These are concrete actions: prevent interest accrual, know the cashback cap, and watch foreign transaction costs if you travel.
Alternatives worth considering
For those who want broader rewards, a travel-oriented bank card or a high-return fintech card may outpace DiDi for non-ride spending. For drivers who prioritize instantaneous funds and lower service friction, a fintech debit or payroll-integrated product could be superior. Yet DiDi’s ecosystem advantage—seamless integration with ride payments and targeted merchant deals—keeps it competitive for its niche. Comparison metrics like net effective reward rate and total cost of ownership reveal the real winners.
Three golden rules to evaluate any rideshare credit product
1) Net Reward Rate: Calculate cashback minus expected interest and common fees across a year; that is your usable yield.
2) Alignment with Spend: Match highest-reward categories to at least 60% of your routine expenses—otherwise the best rates are theoretical, not practical.
3) Timing Discipline: A disciplined billing-cycle routine eliminates carried interest, turning advertised cashback into real savings.
Close: the honest ledger and the path forward
These metrics turn speculation into measurable decisions and show where DiDi’s product fits: a sensible bridge between platform convenience and financial discipline. Look for the card’s strengths where you spend most, keep the balance zeroed when possible, and weigh annual fees against predictable cashback flows. Final thought—DiDi’s wallet is most valuable when used with care; it solves a daily friction with a small, consistent edge. DiDi Finanzas.